BondbloX

Screenshots
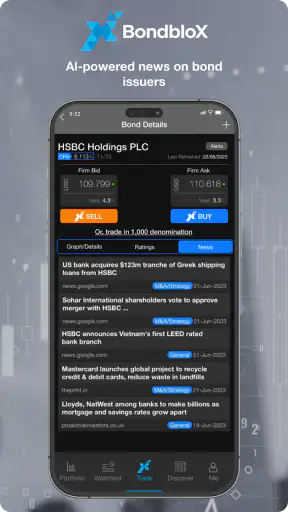
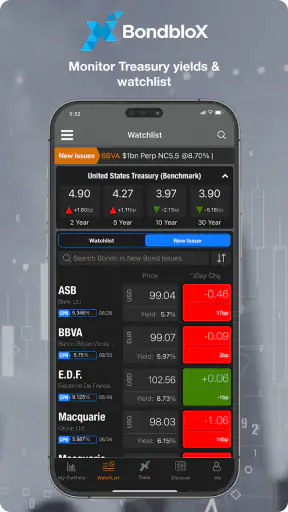
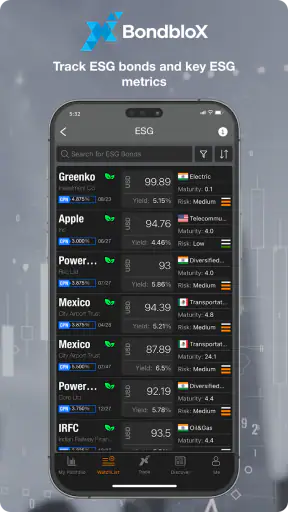
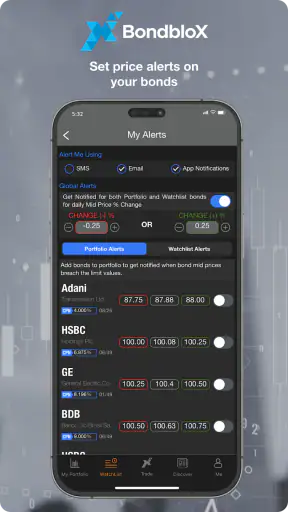
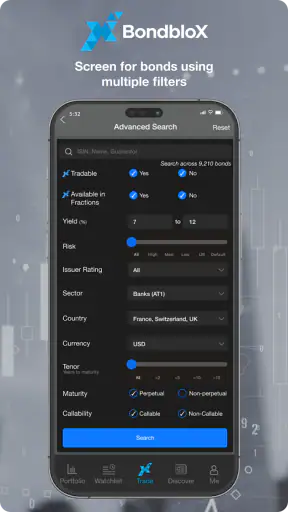
Details
- Rating
- 8.00 reviews
- Version
- 6.70
- Developer
- BondbloX Pte. Ltd.
Analysis by Norviv
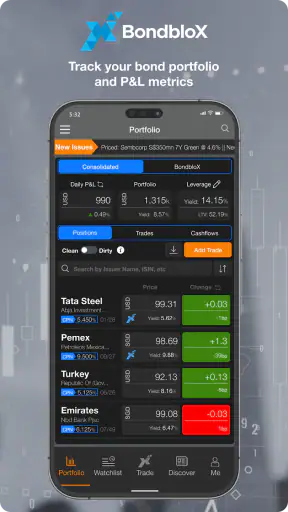
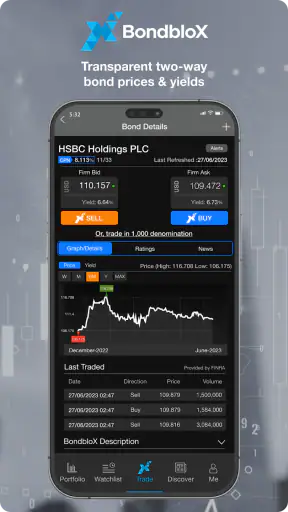
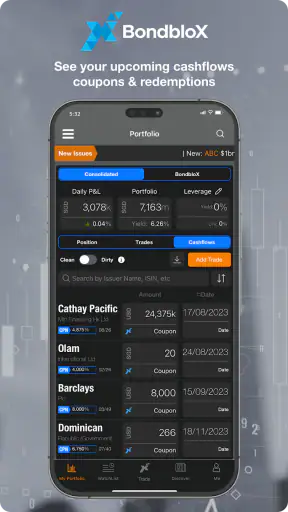
BondbloX is a finance app from BondbloX Pte. Ltd. that I would describe as a compact doorway into bond trading, market information, and analytics. I approached it less like a casual money-management tool and more like a specialist companion for someone who wants to examine fixed-income opportunities from a phone. The app is free to download, carries an Everyone age rating, and has passed the early novelty stage: it was released on October 25, 2017, and the current version is 6.70.
My first impression is that this is not trying to replace a budgeting app, a banking app, or a broad investment dashboard. Its focus is narrower and more useful for the right person. If you are interested in bonds and want relevant information in one mobile experience, it has a clear purpose. If you simply want to track household spending or buy a familiar stock with minimal reading, the specialist angle may feel unnecessary.
How BondbloX feels in its current form
The app’s identity is built around bond trading, market data, and analytics rather than general personal finance. That distinction matters before you install it. I would not open it expecting colorful spending charts, bill reminders, or a guided lesson in basic money management. I would open it when I want to investigate fixed-income products, compare information, and think through whether a bond deserves further attention.
That makes the experience potentially valuable for a self-directed investor who is comfortable asking questions such as how an issuer, maturity, yield, and market conditions fit together. It also makes the app less forgiving for a complete beginner. A finance app can be free and still demand time, because the real cost may be the effort needed to understand what you are looking at.
The current version, 6.70, is important context for existing users. It shows that the product is still being maintained as a living app rather than being left in an untouched early release. I would treat that as a positive sign for usability and continuity, but not as proof that every part of the experience has been redesigned. A version number tells me where the product is now; it does not automatically tell me how much of the underlying workflow has changed.
BondbloX has more than fifty thousand installs and an average rating of 3.6 from roughly two hundred ratings. I read that combination as a useful caution rather than a verdict. There is enough adoption to suggest that the concept has found a real audience, while the middling score reminds me that specialist finance apps can produce very different experiences depending on a user’s expectations, device, market familiarity, and tolerance for research.
A practical way to use it during a normal investing routine
Imagine I am reviewing my finances on a Sunday evening and deciding whether I want to investigate bonds instead of leaving all my savings in a basic deposit account. I would not use BondbloX as a one-tap decision machine. I would begin by identifying the type of bond exposure I am looking for, then use the app’s information and analytics to narrow my questions. The useful outcome is not simply finding a product; it is building a more disciplined shortlist for further checking.
Stories Picked for You

Life360 Works Better When Your Household Agrees on What to Share

YouVersion Bible Fits Scripture into Everyday Phone Routines

Matchington Mansion Review: Match-Three Puzzles With a Place to Restore

Android Auto Shows Why Safer Driving Software Does Less

Google Find Hub Runs on Shared Devices and Quiet Trust

Sygic GPS Navigation: The Ultimate Offline Travel Companion
For example, I might note a bond that appears interesting, record why it caught my attention, and then compare its terms with my personal time horizon and need for access to cash. That workflow turns the app into a research notebook with market relevance. It also prevents a common mistake: confusing the presence of attractive-looking data with a complete investment decision.
One of the more useful habits is to separate discovery from commitment. Use the app to discover possibilities, then pause and verify the details that matter to you before acting. This is especially important when a bond’s apparent return looks appealing but the maturity, issuer risk, liquidity, or currency exposure does not suit your circumstances.
A second practical insight is to use analytics comparatively rather than in isolation. A single figure can look persuasive without context. Looking at several opportunities through the same questions—income, maturity, risk, and suitability—should produce a better decision process than chasing whichever entry first appears attractive. The app’s value increases when I bring a consistent checklist to it.
Who will get the most from it
I see the strongest fit in three groups. The first is an investor who already understands basic bond vocabulary and wants a mobile-focused way to explore opportunities. The second is a financially curious user who is willing to learn and wants to move beyond savings accounts without jumping straight into complicated professional software. The third is someone who already follows fixed-income markets elsewhere and wants another place to examine bond-related information.
It may also suit a user who prefers research before contacting a broker or making an investment decision. In that case, the app can help organize the first stage of investigation. I would still treat it as one part of a wider process, because a mobile interface cannot remove the need to understand the product itself.
On the other hand, I would skip it if my main goal were expense tracking, automated saving, retirement planning, or a simple overview of all my accounts. A conventional personal-finance app would be a better match for those needs. I would also hesitate if I wanted extensive educational guidance from the first screen. BondbloX’s subject matter is specialized enough that a beginner may need another source to explain terminology and investment risks.
What the version history means for users
The move from the original release in 2017 to version 6.70 suggests a product that has had time to evolve. For me, the most relevant question is not whether the number looks large, but whether the current build feels dependable for the tasks I actually need. Mature software often benefits from years of correction and refinement, yet age can also leave behind navigation decisions that newer competitors would handle more smoothly.
Existing users should therefore approach the current release with a practical test. Can I find the information I need without repeatedly retracing my steps? Can I compare opportunities without losing the context of the previous one? Can I understand what each screen is asking me to interpret? Those questions matter more than the version label alone.
New users should also remember that an update does not mean the app has become a complete investment platform. Product evolution can improve access to data and analytics while leaving the user responsible for judgment. I appreciate that distinction because it keeps expectations realistic: the app can support research, but it should not become a substitute for understanding risk.
The free price lowers the barrier to trying the experience, although in-app purchases are listed from $21.99 to $59.99 per item. That makes it important to think about the free portion as an evaluation stage rather than assuming every useful capability is included without cost. Before paying for anything, I would first decide whether the app’s information is relevant to my investing routine and whether the added value justifies the purchase for my specific use.
Where it stands beside familiar finance alternatives
Compared with a standard banking app, BondbloX is more focused on investment research and less focused on everyday cash management. A bank app is usually the place I check balances, transfer money, and review transactions. This app is the place I would turn when the question is more specialized: what bond opportunities deserve attention, and how can I examine them with more structure?
Compared with a stock-trading app, its appeal is not the same kind of fast-moving, headline-driven experience. Bonds require attention to terms and time horizons, so the best use of a bond-focused tool is often slower and more deliberate. Someone who wants instant trading across many asset classes may prefer a broad brokerage app. Someone who wants to concentrate on fixed income may appreciate the narrower scope here.
Compared with a spreadsheet, BondbloX should offer a more purpose-built starting point for bond-related research. A spreadsheet gives me control over my own calculations, but I must collect and organize everything myself. The trade-off is that a spreadsheet can be easier to customize, while a dedicated app can be easier to consult when I want information shaped around a particular financial subject.
Compared with a general market-news app, the specialist focus is potentially its biggest advantage. News apps can provide context but may scatter bond information among stocks, commodities, currencies, and economic headlines. BondbloX makes more sense when I want the fixed-income angle to remain central. The downside is that a narrower lens may not provide the broad portfolio perspective I need on its own.
Friction points I would consider before relying on it
The average rating of 3.6 tells me not to assume the experience will be universally smooth. I would pay close attention to navigation, clarity, and how much interpretation each screen requires. Finance apps are judged harshly for good reason: a confusing label or poorly understood figure can affect a serious decision, even when the underlying information is useful.
Another limitation is the gap between research and action. Finding a bond or studying analytics is not the same as completing a suitable investment. I would not use the app as my only source for checking personal suitability, tax implications, currency concerns, or the practical details of an eventual transaction. Those checks belong in the decision process even if the app makes discovery easier.
The in-app purchase range is another point of friction. Free access is helpful for testing the concept, but paid items can change the value calculation. I would avoid subscribing or purchasing simply because a feature sounds advanced. First I would use the available experience to identify a repeated problem in my workflow; only then would I consider whether a paid item solves it often enough to be worthwhile.
There is also a learning curve that may not be obvious from the short store description. Bond investing is not difficult only because of the interface. It involves concepts that behave differently from the simple “buy low, sell high” thinking many people bring from stock apps. If I were introducing this app to a friend, I would recommend learning the basics of maturity, income, issuer risk, and liquidity alongside using it.
Three habits that make the app more useful
My first recommendation is to create a written decision rule before browsing. I would decide what matters most—income, a particular time horizon, diversification, or preserving access to cash—and use that rule to filter my attention. Without one, analytics can encourage endless browsing and make the most visually prominent opportunity feel more important than it really is.
Second, I would keep a simple record of why I saved or investigated an opportunity. The reason may be a maturity that fits my plans, a yield that deserves comparison, or a desire to understand a particular issuer. Revisiting that reason later helps me distinguish a considered idea from a momentary reaction to a number.
Third, I would use a two-stage review. In the first stage, I would explore and compare. In the second, I would independently recheck the terms and ask whether the opportunity still fits my circumstances. This is a small change in routine, but it reduces the risk of treating an app’s convenient presentation as the final word.
What I would like to see next
For future development, I would watch how BondbloX improves the bridge between specialist information and everyday understanding. The strongest next step would be clearer context around analytics, especially for users who know enough to be interested but not enough to interpret every bond detail confidently. Better explanation can make a finance app more useful without turning it into a simplistic beginner product.
I would also watch whether the experience becomes easier to compare across opportunities and easier to revisit after an initial search. Those are the moments when a research app proves its value: not when it displays one interesting item, but when it helps me make a consistent, traceable decision over time.
Existing users should watch updates for changes that affect navigation, data presentation, and the balance between free access and paid items. New users should watch their own behavior: if the app helps them ask better questions, it is earning its place; if it merely encourages impulsive browsing, a simpler or broader alternative may be healthier.
My recommendation
I would recommend BondbloX to a patient, self-directed investor who specifically wants a bond-focused mobile tool and is willing to verify important details before acting. Its free entry point makes experimentation straightforward, while the current version shows an established product that has continued beyond its original release. The specialist focus is its clearest strength.
I would not recommend it as a universal finance app or as a replacement for financial education, a personal budget tool, or a full brokerage relationship. The middling rating, specialist learning curve, and paid in-app items mean I would test it carefully rather than commit immediately. For the right user, though, it can turn bond research into a more organized mobile routine.
My final view is that BondbloX is most valuable when used as a research companion, not an automatic decision-maker. I would open it with a clear question, compare opportunities using the same criteria, and confirm the important terms elsewhere before investing. If that sounds like the way you already approach money decisions, the app is worth exploring. If you want effortless personal finance or instant, broad-market trading, another category of app will probably serve you better.
Frequently Asked Questions
01What is BondbloX and what can I use it for?
BondbloX is a digital investment platform focused on fractional bond investing. It allows eligible users to access selected fixed-income opportunities without necessarily purchasing an entire traditional bond, which can require a high minimum investment. Through the app, users can review available bond offerings, examine key terms, and manage investments from a mobile device. Availability, product selection, and account features may vary by country and user eligibility.
02How does fractional bond investing work in BondbloX?
BondbloX divides eligible bonds into smaller digital units, making certain investments more accessible than buying a full bond directly through a conventional brokerage. Before investing, users should review the bond’s issuer, maturity date, coupon or yield, currency, minimum investment, and applicable fees. Fractional ownership does not remove investment risk, and the value or liquidity of an investment can be affected by market conditions and issuer performance.
03Is BondbloX safe and regulated?
BondbloX uses account verification and security measures intended to protect users and support compliant investing, but no financial application can eliminate every risk. The level of regulatory protection depends on the entity providing the service, the user’s location, and the specific product purchased. Users should confirm the platform’s current licensing information, custody arrangements, investor protections, and terms before depositing money or purchasing any bond.
04What fees and risks should I consider before using BondbloX?
Potential costs may include transaction charges, platform or custody fees, currency-conversion costs, withdrawal charges, and other expenses described in the applicable fee schedule. Bond investing also carries risks, including issuer default, interest-rate changes, currency fluctuations, price volatility, and limited secondary-market liquidity. A displayed yield is not a guarantee of profit. Carefully read the product documents and calculate the total cost before investing.
05Who can open a BondbloX account, and what is required to get started?
Account availability depends on your country, age, residency, and the platform’s current eligibility rules. New users will generally need to provide personal information, verify their identity, and complete any required regulatory checks before investing. You may also need a supported payment method and documents explaining the source of funds. Check the latest requirements in the app because onboarding rules and supported regions can change.


